All Categories
Featured
Consumer Advice for Selecting 2026 Medicare Insurance
Table of Contents
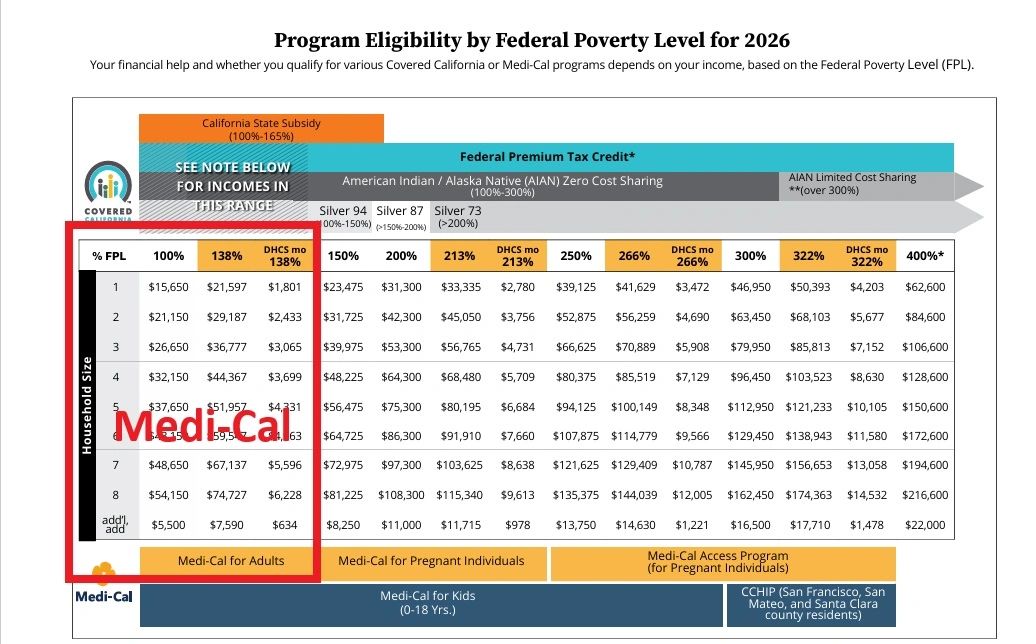
How does the 2026 aid cliff affect Pennsylvania family health insurance? The return of the 400 percent FPL subsidy cliff in 2026 roughly $128,600 yearly income for a family of four significantly increased costs for middle-income Pennsylvania families on Pennie.
Nevertheless, even families above the APTC threshold might have kids eligible for CHIP if home income is listed below 319 percent FPL per-child, considerably reducing overall household coverage cost. Can Pennsylvania families enroll in CHIP beyond open registration? Yes. Pennsylvania CHIP registration is open year-round there is no open enrollment duration restriction for CHIP or Medical Help.
Children who get eligibility due to income changes, loss of other protection, or other scenarios can be registered in CHIP at any point throughout the year. CHIP, Medical Support, and Pennie market plans often collaborate for Pennsylvania households.'s licensed PA brokers confirm eligibility for every single household member and total enrollment at no extra cost.
is not associated with Pennie, the Pennsylvania Department of Human Providers, the Pennsylvania Insurance Coverage Department, or any provider including CHIP providers. The company assists Pennsylvania citizens compare plans and register in coverage at no extra expense.
An insurance program jointly moneyed by states and the federal government that offers health insurance coverage to low-income kids and, in some states, pregnant ladies in families who earn too much earnings to certify for Medicaid Can not afford to acquire private health insurance protection.
Navigating Medicare Part D Coverage for 2026
We discovered yesterday that the typical cost of a family medical insurance policy through a company reached almost $27,000 this year, 6% higher than what it cost in 2024. As if that weren't disconcerting enough, researchers are predicting that the total likely will soar towards $30,000 next year since of rising medical expenses and the unrelenting pressure insurance companies are under from Wall Street to increase their earnings.
Despite repeated guarantees from insurers that we can rely on them to hold down the expense of health care and consequently the premiums they charge there are now several years of evidence from scientists like KFF, which tracks yearly modifications in employer-sponsored protection that they have not and can not deliver on their pledges.
A health insurance coverage policy today is generally less valuable than it was a decade ago since families need to invest increasingly more money out of their own pockets every year before their protection starts. In addition, they are much more most likely to be notified that their insurers will not cover the care their medical professionals state they require.

That is a rate of increase much greater than basic inflation and also higher than medical inflation. Not just has the overall cost of an employer-sponsored strategy escalated, so has the share of premiums workers must pay. This year, companies subtracted approximately $6,850 from their employees' paychecks for family protection, up from $4,823 in 2014, a 42% increase.
Insurance in Rancho Santa Margarita CAThe Affordable Care Act, to its credit, instituted a cap on out-of-pocket expenses in 2014, however that cap has been increasing every year together with premiums. (The U.S. Department of Health & Person Providers sets the out-of-pocket max every year, pegging it to the average boost in premiums.)In 2014 the out-of-pocket cap for a household policy was $12,700.
Understanding HMO Vs PPO Health Insurance
And bear in mind that the cap only uses to in-network care. If you head out of your insurance company's network or take a medication not covered under your policy, you can be on the hook for hundreds or thousands more. While a lot of employer-sponsored plans have caps that are considerably lower, lots of individuals and families reach the legal max every year.
Insurance providers said their 2024 earnings were rather depressed since more of their health strategy enrollees went to the physician and selected up their prescriptions last year. Financiers were furious that insurance providers couldn't keep that from happening, as you'll see in the charts listed below.
Overall, the stock prices of the huge insurance corporations have actually increased steadily over the years as we and our employers have had to invest more for policies that cover less. For example, UnitedHealth Group, the greatest of the seven, saw its stock rate increase 483% between 2014 and 2024 from $85.31 a share on Dec.
31, 2024. Many of the other business saw similar growth in their shares over that time duration. By contrast, the Dow Jones Industrial Average increased 139% (from $17,823.07 to $42,544.22), and the S&P 500 increased 186% (from $2,058.90 to $5,881.63) throughout the same period. Back to those premiums and out-of-pocket requirements.

Latest Posts

Finding Affordable Family Health Insurance in 2026
Why to Use IUL for Retirement Planning
Top-Rated IUL Benefits for Retirement Income